Private PPO vs. ACA Marketplace Plans
The ACA Marketplace and private PPO coverage are built for two different situations, and most of the confusion between them comes from comparing a sticker price instead of comparing the two things side by side.
Here is the plain version: if you qualify for a meaningful subsidy, the Marketplace is usually very hard to beat, and a licensed advisor should tell you so. If you do not qualify — which is common for self-employed people whose income is above the subsidy cliff — you are paying the full unsubsidized premium, and that is where private PPO coverage is worth a serious look.
The alternative
ACA Marketplace
Guaranteed-issue coverage with subsidies tied to income, sold during a fixed annual window.
- Nobody can be turned down or rated up for health history
- Premium tax credits can make coverage very inexpensive at lower incomes
- Every plan covers the ten essential health benefits, including maternity and mental health
- Unsubsidized premiums for a healthy applicant are often the highest number on the page
- Many regions are served mainly by narrow HMO networks with referral requirements
- Deductibles on bronze plans commonly run $5,000 and higher
Private PPO
Private PPO coverage
Medically underwritten plans with broad national networks, available to apply for any day of the year.
- Broad nationwide PPO networks — see specialists without a referral
- Apply any day of the year, not only during open enrollment
- Lower premiums are common for applicants in good health
- Deductible and copay structures are usually more predictable
- Approval is not guaranteed — health history is reviewed
- No premium tax credits: the price you see is the price you pay
Side by side
Who can be approved
ACA Marketplace
Everyone, guaranteed
Private PPO
Reviewed — health history matters
Subsidies available
ACA Marketplace
Yes, based on income
Private PPO
No
Typical unsubsidized premium
ACA Marketplace
Among the highest available
Private PPO
Often materially lower for healthy applicants
Deductible range
ACA Marketplace
$5,000–$9,000+ on bronze
Private PPO
As low as $0 depending on the plan
Network type
ACA Marketplace
Often narrow local HMO
Private PPO
Broad nationwide PPO
Specialist referrals
ACA Marketplace
Usually required
Private PPO
Usually not required
Enrollment window
ACA Marketplace
About six weeks a year
Private PPO
Any day of the year
Pre-existing conditions
ACA Marketplace
Always covered
Private PPO
Covered on the plans we place — reviewed at application
Coverage when you travel
ACA Marketplace
Emergency only, in most cases
Private PPO
In-network nationwide
Should I just take the subsidy?
If your household income puts you well inside the subsidy range, very often yes — and an honest advisor will say so rather than talk you out of it. Premium tax credits can reduce a Marketplace premium to a fraction of its list price, and no private plan competes with that. The question only gets interesting when your income is above the threshold, or your income varies enough that a year-end reconciliation could claw the credit back.
Is a PPO really that different from an HMO in practice?
It is, and it usually shows up at the worst possible moment. Under a narrow HMO you generally need a primary-care referral before a specialist will see you, and care outside your home network is not covered except in an emergency. A broad PPO lets you book the specialist directly and keeps you in network in most of the country. If you travel, work across state lines, or have a specialist you already trust, that difference is the whole decision.
What does medically underwritten actually mean?
It means the carrier looks at your health history before issuing the plan, the way life insurance works. Some conditions lead to a higher rate, some to a decline, and many are simply covered. It is why the premium can be lower — the pool is healthier. It is also why private coverage is not the right answer for everyone, and why a real conversation beats an instant online estimate.
Can I switch mid-year?
Into private PPO coverage, yes — applications are accepted year-round. Moving back onto a Marketplace plan outside open enrollment requires a qualifying life event, such as losing employer coverage, moving, marrying, or having a child. That asymmetry is worth understanding before you drop anything.
Best for
ACA Marketplace
People who qualify for a subsidy, anyone with significant ongoing medical needs, and anyone who needs guaranteed acceptance regardless of health history.
Best for
Private PPO
Healthy self-employed people and families above the subsidy line who want a broad national network and need coverage outside open enrollment.
Check your subsidy first. If it is real, take it. If it is not — and for a large number of self-employed households it is not — a private PPO usually buys a broader network and a lower monthly cost than the unsubsidized Marketplace plan sitting next to it. A licensed advisor can run both numbers with you in one call.
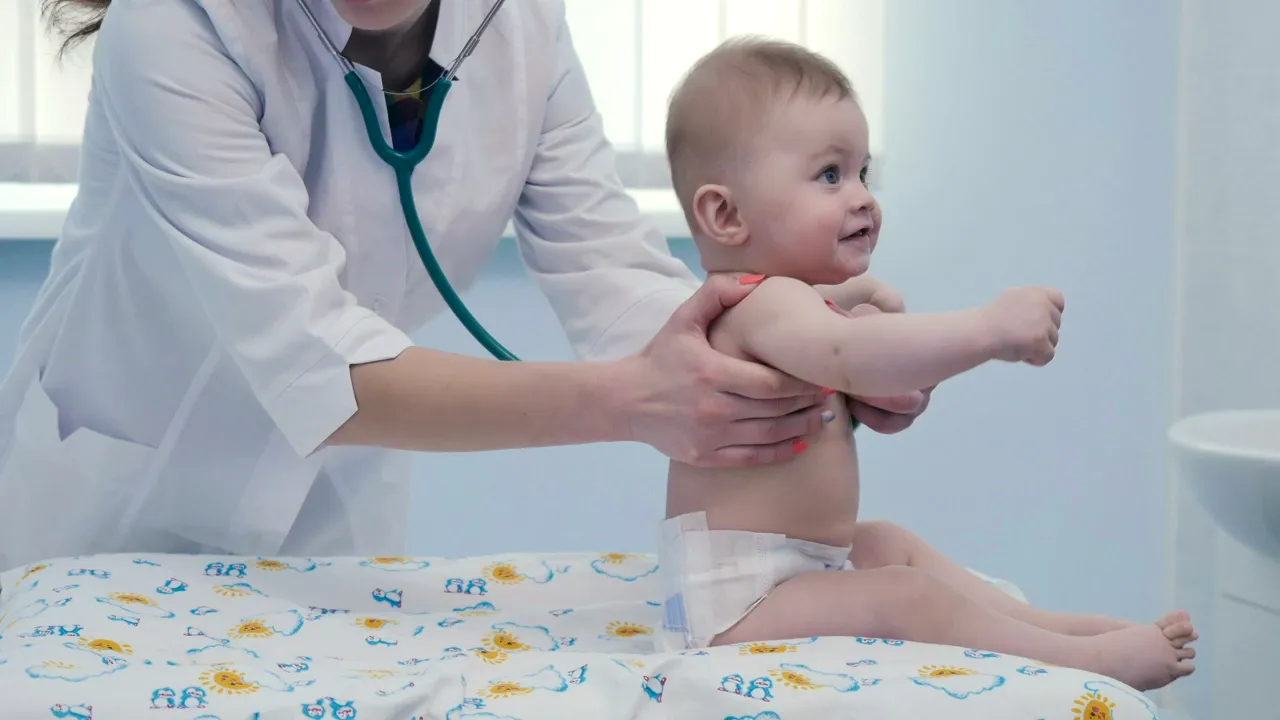
The difference shows up at the front desk.
Network, deductible and out-of-pocket maximum are abstractions until somebody asks for your card. That is the moment these comparisons are written for.
- Which doctors take the plan
- What you pay before coverage starts
- The most a bad year can cost
Plans from nationally recognized carriers
Find out which one
applies to you.
A licensed advisor will tell you honestly which side of this comparison you belong on — even when the answer is the other one.
Keep reading
- Licensed advisors in all 50 states
- Pre-existing conditions covered
- Apply any day of the year
Free plan review
Step 1 of 5
Let's find your coverage