Health coverage is confusing on purpose. We are the other thing.
American Healthcare Choice connects people who do not get insurance through an employer with licensed advisors who can walk them through private PPO coverage — honestly, at any time of year, including when the honest answer is that something else suits them better.
A referral service, not an insurance company.
We do not underwrite policies, decide who qualifies or issue coverage. We put the right information in front of a licensed advisor so that the call you get is a useful one.
Most of the people we hear from are self-employed, between jobs, working seasonally, or retired before Medicare. Nobody is splitting the premium with them, and the default options are expensive, narrow, or closed for eleven months of the year.
Private PPO plans are medically underwritten. The carrier asks health questions, which is why the coverage can cost less and reach further — and why it is not the right route for everyone.
How we are paid: if you enroll through a licensed advisor, the carrier pays that advisor a commission. You are never charged for the review, and the commission does not change what you pay.
We would rather lose the sale than sell you the wrong plan.
Every one of these is something you can hold us to on the call — not a slogan we put on a banner.
One licensed advisor who actually picks up the phone.
Your details go to one person, not a lead auction. You get their name, and they are the one who calls.
Year-round review
Private plans are medically underwritten, which means there is no six-week window. You can apply in March, in July, or the week you lose a job.
Nationwide PPO networks
Broad networks that travel with you, instead of a county-bound HMO that stops working the moment you cross a state line.
Pre-existing conditions covered
We ask about them in step three of the survey for a reason — so the advisor is working with the truth from the first minute.
We will send you elsewhere
If Medicaid, a subsidized Marketplace plan or your spouse’s employer plan is the better deal, that is what you will be told.
See the honest comparisons
A licensed advisor who actually picks up the phone.
We are not an algorithm that spits out a plan. You submit what you need, a licensed advisor reviews it, and then a human being walks you through the real options — including the ones that are not ours to sell. The advisor handles the plan conversation and the paperwork. You make the decision.
- They read your answers before they dial.
- They tell you what a plan does not cover, not just what it does.
- They do not need a decision on the call.
Four things you can hold us to.
- 1
We say when we are not the answer
Medicaid, a subsidized Marketplace plan, a spouse's employer plan, staying on COBRA mid-treatment — all of these beat us for some people. An advisor who cannot say that out loud is not giving you advice, they are reading a script.
- 2
One advisor, one call
Your details are not sold, shared or auctioned. They go to a single licensed advisor who reads them and calls you once. If you say no, that is the end of it.
- 3
No invented numbers
Your actual premium comes from a carrier underwriting your actual application — not from a calculator on a marketing page. Until then, nobody should be promising you a number.
- 4
Plain English, always
Deductible, co-insurance, out-of-pocket maximum, underwriting. These decide what you pay in a bad year, and you are entitled to have them explained without jargon before you sign anything.
Four steps, and you can stop at any of them.
Five short questions: your state, who needs coverage, whether pre-existing conditions are in the picture, and how soon you need it. About thirty seconds.
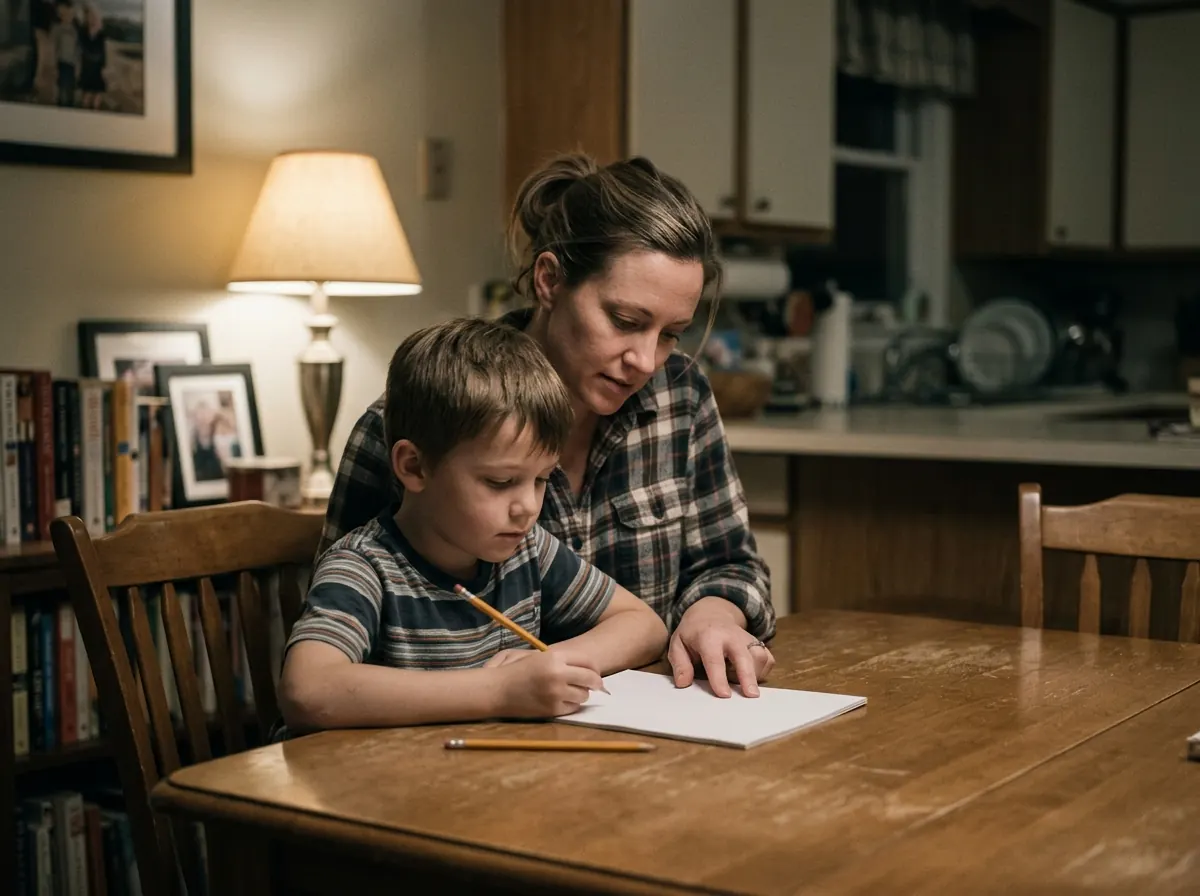
What a call with an advisor actually sounds like.
- Network check
“I called about a plan I had already picked out and the advisor talked me out of it. She said the network did not include the hospital ten minutes from my house. I would never have checked.”
- Off-cycle
“My contract ended in March, which the Marketplace does not care about. Being able to apply in the middle of the year was the whole reason this worked.”
- Pre-existing conditions
“I said up front that I have a condition I need covered. Nobody got cagey about it — they just told me which direction that pushed things and why.”
- Sent elsewhere
“He worked out that I would qualify for a subsidy and told me to go to the Marketplace instead. He did not make a cent from that call.”
- After a layoff
“COBRA wanted more than my mortgage. One call, two real alternatives, and an honest note about what each one gives up.”
- Small business
“I run a four-person shop. I was told for years I was too small for a group plan and nobody ever offered me a second option until this call.”
- Keeping a doctor
“The first thing she asked was which doctors we wanted to keep. Not my budget. That told me a lot about how the rest of the call would go.”
- Before 65
“Retired at 61 and found out what four years without Medicare actually costs. Having someone lay out the bridge options in plain English was worth the half hour.”
- Gig work
“I drive for two platforms and neither of them covers me. I had assumed I had to wait until November to do anything about it.”
- Prescriptions
“He told me straight out that one of my medications would not be covered the way I wanted on the plan I was asking about. Nobody had mentioned that before.”
- Family coverage
“Three kids, two of them in sports, and I wanted to know what an urgent care visit actually costs. We went line by line until I understood it.”
- Seasonal income
“My work is seasonal so my income is not. She built the comparison around what the months with no work look like, not the good months.”
- No pressure
“I was ready to be sold to and it never happened. He answered the questions, sent me the details, and left the decision with me.”
- Understanding the plan
“The deductible number is the one everybody talks about. She was the first person to explain what the out-of-pocket maximum meant for us instead.”
Hover or focus the row to pause it.
Honest advice starts
with four questions.
No payment details, no login, no credit check, and no obligation to enroll in anything. Just your state, who needs covering, and where to reach you.
- Licensed advisors in all 50 states
- Pre-existing conditions covered
- Apply any day of the year
Free plan review
Step 1 of 5
Let's find your coverage